
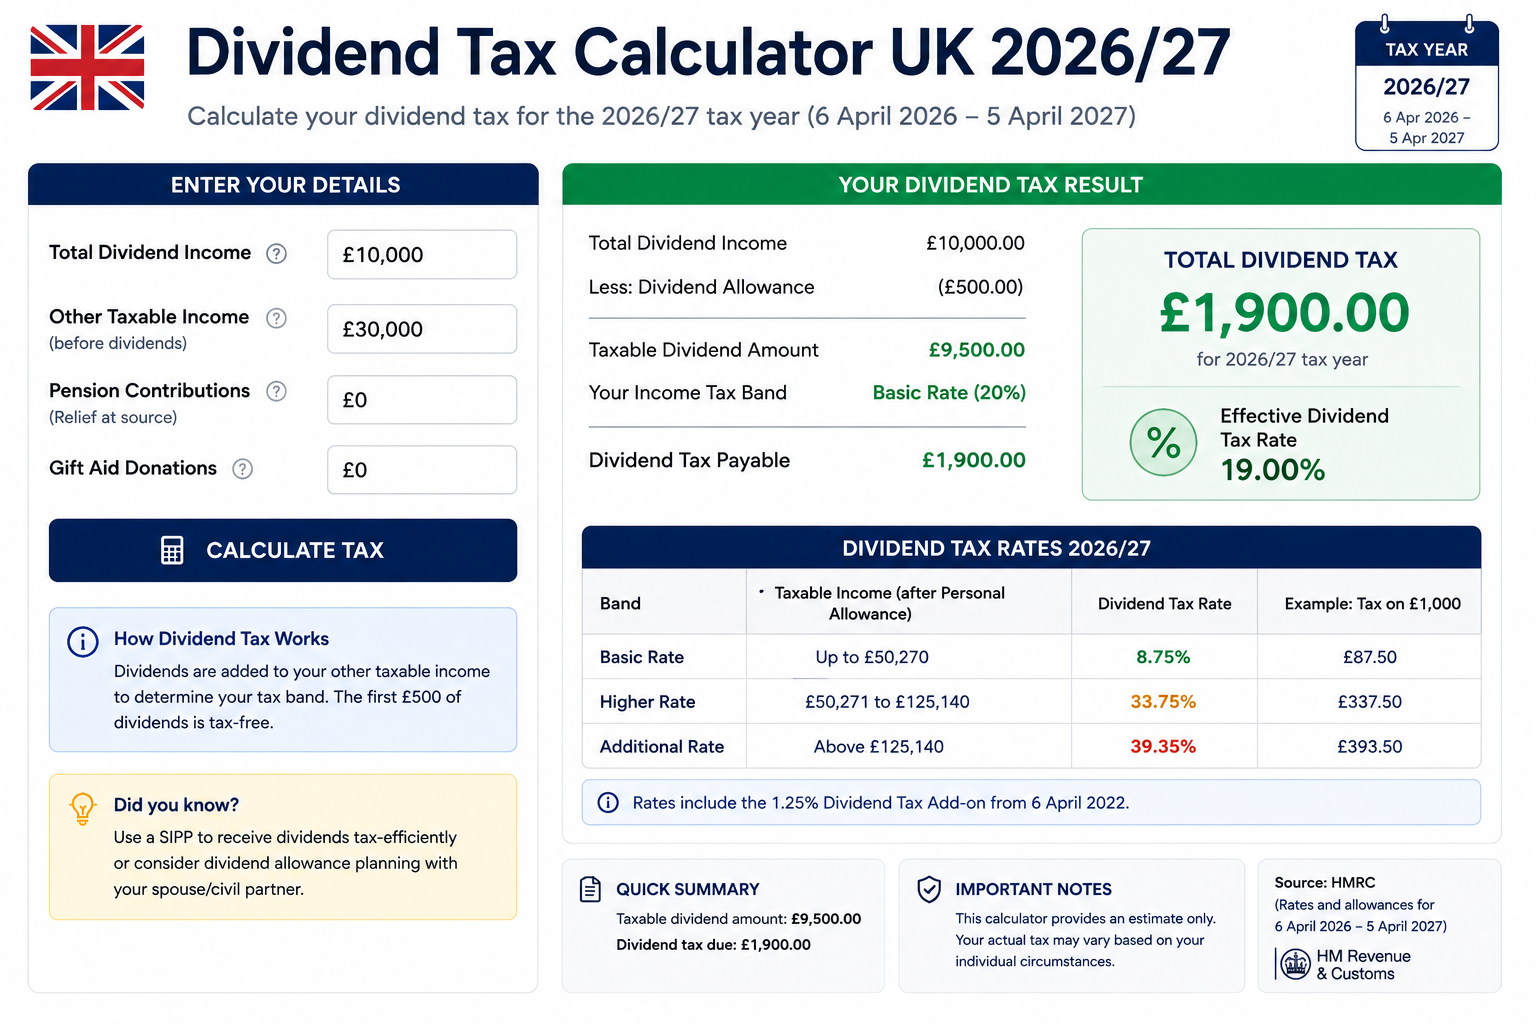
Dividend Tax Calculator UK 2026/27
Estimate 2026/27 dividend tax using the £500 dividend allowance and current dividend rates.Other taxable income before Personal AllowanceDividend income
Calculate
Result—
Result—
Result—
Result—
This page freezes its main assumptions to tax year 2026/27 so historic and future rates are not mixed. It focuses on dividend-income taxation; Shareholders and investors can use this tool when dividends sit on top of salary or other taxable income. The calculator therefore shows the inputs that matter most instead of inventing missing payroll details.
How to Use the Dividend Tax Calculator UK 2026/27
Dividend income is stacked on top of other taxable income, so the calculator asks for other income as well as dividends. Dividend tax needs other income because dividends occupy tax bands after earnings. A flat rate on all dividends would be wrong for someone who crosses from basic into higher rate.
The ordinary rate is 10.75%, upper rate 35.75% and additional rate 39.35% for 2026/27. The tool is a mainstream individual estimate and does not model every company-owner planning issue.
2026/27 Personal Allowance
Personal Allowance matters to dividend-income taxation because it determines how much income enters the tax bands. The standard 2026/27 amount is £12,570. Once adjusted net income exceeds £100,000, £1 of allowance is withdrawn for each £2 of excess income, leaving no standard allowance at £125,140. In the context of Dividend Tax Calculator UK 2026/27, the number only matters when it changes dividend tax. This page therefore ties the rule back to the £500 allowance and stacking above other income, which is the decision path most useful for shareholders and investors.
Income Tax Rates Used in the Model
The England, Wales and Northern Ireland reference used here has a £37,700 taxable basic-rate band at 20%, followed by 40% up to £125,140 of taxable income and 45% beyond. This rate ladder is relevant to dividend-income taxation when the user is not a Scottish taxpayer. For this calculator, the next step is not to apply every tax rule on the site. It is to connect the figure with dividend tax, using the £500 allowance and stacking above other income. That narrower scope is intentional for shareholders and investors.
The calculation is intentionally narrow: £500 allowance and band stacking. Unrelated tax bands are not applied simply because they exist elsewhere in the UK system. Shareholders and investors can use this tool when dividends sit on top of salary or other taxable income.
National Insurance and Other Deductions
The NI component is conditional on the purpose of the page. A salary or take-home calculation uses the standard 8% then 2% Class 1 employee pattern, while dividend-income taxation may require no NI line at all. Keeping the components separate makes the result easier to audit. The reason it appears on Dividend Tax Calculator UK 2026/27 is page-specific: dividend tax can be misunderstood if the £500 allowance and stacking above other income is left implicit. The wording here is aimed at shareholders and investors and the result should be read on that basis.
Student-loan deductions sit outside Income Tax and use plan-specific 2026/27 thresholds: £26,900 for Plan 1, £29,385 for Plan 2, £33,795 for Plan 4, £25,000 for Plan 5 and £21,000 for postgraduate loans. The first four plans charge 9% above threshold, while postgraduate loans use 6%. BritTaxCalc treats this differently on Dividend Tax Calculator UK 2026/27 because the core output is dividend tax. By focusing on the £500 allowance and stacking above other income, the page avoids suggesting that the same rule has identical importance on every calculator.
Who Should Use the Dividend Tax Calculator UK 2026/27
Shareholders and investors can use this tool when dividends sit on top of salary or other taxable income.
The calculation centres on £500 allowance and band stacking. The same dividend amount can face different rates depending on how much of the basic and higher bands have already been occupied by other income. Keeping those drivers explicit makes it possible to rerun the same scenario after a pay rise, code change or new tax year without guessing which assumption moved.
Use the result to understand dividend-income taxation, then move to a specialist page if another income source or deduction becomes material. A page that tries to solve salary, dividends, capital gains, benefits, pensions and multiple jobs in one default calculation would hide more assumptions than it explains. On Dividend Tax Calculator UK 2026/27, this point is included because the calculator is specifically about dividend tax. The practical test is the £500 allowance and stacking above other income; that keeps the explanation relevant to shareholders and investors rather than turning it into a generic tax paragraph.
Worked Examples for Dividend Tax Calculator UK 2026/27
- Example 1: with £25,000 of other income and £3,000 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 2: with £29,500 of other income and £4,800 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 3: with £34,000 of other income and £6,600 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 4: with £38,500 of other income and £8,400 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 5: with £43,000 of other income and £10,200 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 6: with £47,500 of other income and £12,000 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 7: with £52,000 of other income and £13,800 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
- Example 8: with £56,500 of other income and £15,600 of dividends, only dividends above the £500 allowance enter the dividend-rate stacking calculation.
Common Mistakes to Avoid
- Using 2025/26 thresholds on a page labelled 2026/27.
- Applying the highest marginal rate reached to the whole salary.
- Forgetting the Personal Allowance taper above £100,000 where it applies.
- Mixing Scottish employment-income rates with rest-of-UK bands.
- Treating National Insurance or student loans as if they were part of Income Tax.
- Assuming an annual estimate must equal every monthly PAYE deduction.
Related BritTaxCalc Calculators
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Open the focused 2026/27 calculator.
Dividend Tax Calculator UK 2026/27 FAQs
What is the dividend allowance in 2026/27?
£500.What changed this year?
The ordinary rate rose to 10.75% and the upper rate to 35.75%; the additional rate remains 39.35%.Which tax year is this calculator for?
The calculation is labelled for 6 April 2026 to 5 April 2027.Can actual payroll differ?
Yes. Pay frequency, cumulative PAYE, tax codes, benefits and other deductions can change a real payslip.